

Products are selected by our editors, we may earn commission from links on this page.
The Trump administration has begun sending $500 Affordable Care Act refund checks to nearly 1 million people across 30 states, but the payments are aimed at a particularly important group of marketplace customers: people who paid the full cost of their insurance without receiving federal premium assistance. The Treasury Department began mailing the checks in late September, with eligible recipients expected to receive a payment along with a letter from President Donald Trump. The administration says the refunds are meant to return excess exchange user fees that were built into premiums for people who purchased coverage through the federal HealthCare.gov marketplace.
The group receiving most of the money is largely made up of people with incomes above 400% of the federal poverty level, a category that became especially vulnerable after enhanced ACA tax credits expired at the end of 2025. Under the expanded credits that were available through 2025, people above the traditional 400% income cutoff could still qualify for financial help, but that assistance disappeared for 2026 when the enhanced credits were not extended. That means many middle- and upper-middle-income households that previously had help with their premiums suddenly became responsible for the full price of their plans.
The refunds therefore arrive at a time when these households are already dealing with substantially higher insurance costs. The White House says the payments will be $500 per eligible person and will go to qualifying enrollees in the 30 states that use the federally operated exchange, including Texas, Florida, Ohio, Michigan and Wisconsin. The administration has identified eligible recipients, meaning people generally do not need to apply separately for the refund.
Why This Group Lost Federal Premium Assistance in 2026
The enhanced ACA premium tax credits were originally expanded during the COVID-19 pandemic and allowed more people to receive assistance, including households whose income was above 400% of the federal poverty level. Those enhanced credits expired after 2025, restoring the traditional income limit for subsidies and leaving many people who had previously received assistance with no federal premium help at all. For 2026 coverage, the 400% threshold was roughly $62,600 for an individual and $128,600 for a family of four, based on the federal poverty guidelines used for determining eligibility.
The financial impact has been significant for some households because losing a subsidy does not simply mean receiving a smaller discount. People above the income threshold can be required to pay the full marketplace premium, even when the underlying insurance plan becomes considerably more expensive. Health policy analysts have pointed out that some older consumers just above the cutoff could face thousands of dollars in additional annual premium costs after losing the enhanced assistance.
That helps explain why the $500 refunds are going disproportionately to people who may feel as though their health insurance costs have suddenly jumped. The payments are not a replacement for the expired premium tax credits, and they do not restore the monthly assistance that many households lost. Instead, they are a one-time payment tied to the administration’s decision to return surplus exchange user fees to certain unsubsidized consumers.
The $500 Refund Comes as Marketplace Costs Have Jumped
The White House says the refunds come from excess user fees collected from insurers that sell plans through HealthCare.gov. Those fees help finance the federal marketplace, including the HealthCare.gov website, call center and enrollment assistance programs, and insurers generally build the cost into premiums rather than listing it as a separate charge for consumers. The administration argues that the fees collected were higher than necessary and that the resulting surplus should be returned to people who paid full premiums.
There is an important disagreement over what those excess funds represent, however. Health policy experts have noted that a surplus in the exchange user-fee account does not necessarily mean consumers were individually overcharged, because the fees are set in advance and the money can be affected by changes in enrollment and federal spending. KFF’s Cynthia Cox also noted that subsidized consumers are generally excluded from the refunds because the government absorbs much of the effect of premium increases for people receiving premium assistance.
That distinction matters because the $500 check can look much larger than the actual financial relief it provides to someone whose premiums increased by thousands of dollars. Critics have argued that the payment does little to address the underlying affordability problem created by the expiration of the enhanced tax credits, while the administration views the checks as a way to return excess fees to people who paid full price for their coverage. Either way, the refund is a one-time payment and should not be confused with an ongoing federal premium subsidy.
What Eligible Americans Need to Know About the Payments
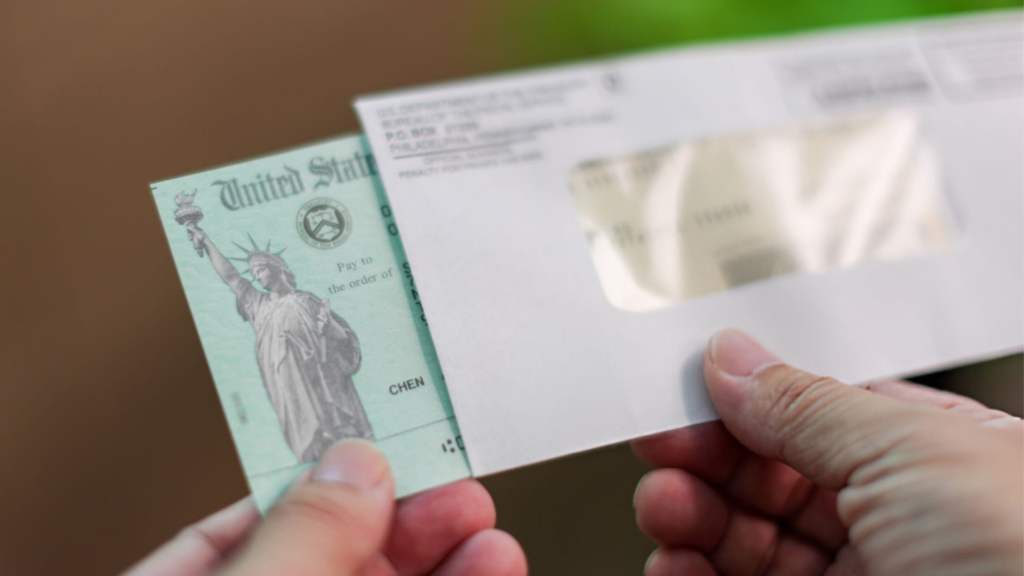
For the nearly 1 million eligible Americans, the refund provides some money back at a moment when health insurance has become considerably more expensive for many unsubsidized marketplace customers. The checks are being sent to people in 30 states, and the largest numbers are expected in states such as Texas and Florida. Households with more than one eligible person could potentially receive multiple payments because the refund is structured as $500 per person.
But the bigger story is what happened before the checks arrived. Many of the people receiving them lost access to federal premium assistance when the enhanced ACA tax credits expired, leaving them exposed to the full cost of marketplace coverage in 2026. For some households, the $500 payment may help with an insurance bill or other expenses, but it is unlikely to make up for the recurring financial assistance they lost when the enhanced credits ended.
The refunds also highlight the complicated financial pressures facing ACA customers this year. While the administration describes the payments as a return of excess exchange fees, health policy experts emphasize that the much larger affordability problem is tied to rising premiums and the loss of enhanced tax credits, which affected access to financial help for millions of people. For unsubsidized enrollees receiving a check, the $500 may be welcome relief, but it does not change the fact that they are now responsible for paying their full marketplace premiums without the federal assistance they had come to rely on.