

Products are selected by our editors, we may earn commission from links on this page.
Thousands of retirees in their late fifties and sixties visit The Villages in Florida every week for a lifestyle preview, drawn in by golf carts, town squares, and nightly entertainment. Many go home and decide not to buy. When asked why, the answer tends to be remarkably consistent: it comes down to money, specifically a layered fee structure the sales tour never adds up into one clear number.
This article was created with the assistance of AI and reviewed by our editorial team for accuracy and clarity.
Buyers Take On Three Separate Recurring Obligations at Once
The Villages operates through Community Development Districts rather than a traditional homeowners association, which means new buyers take on three separate recurring obligations at once. There’s the bond, covering the buyer’s share of infrastructure financing paid over roughly 30 years. There’s an annual CDD maintenance assessment funding streets and common areas. And there’s a monthly amenity fee covering golf, pools, and recreation centers.
Here’s What Each of Those Costs Actually Runs
Each of these costs comes with real dollar figures attached. Bond balances typically range from $10,000 to $40,000 depending on a home’s age and section, paid either as a lump sum or amortized on the annual tax bill. The monthly amenity fee runs around $200 for most buyers. Combined annual CDD assessments, covering both bond and maintenance, commonly range from $1,600 to over $6,000 depending on the district.
Each Fee Escalates on Its Own Separate Schedule
What makes this structure particularly tricky is that each cost escalates on its own separate schedule. The amenity fee is contractually tied to the Consumer Price Index and rises with inflation for as long as someone owns the home, with no ceiling written into the standard agreement. The CDD maintenance assessment gets reset annually by the district board based on actual costs, and the bond accrues interest for its full term if it isn’t paid off upfront.
The Sales Tour Sells Lifestyle, Never the Actual Ledger
The sales preview itself focuses almost entirely on lifestyle rather than the actual ledger involved. Visitors leave able to describe the squares and golf cart paths in detail, but usually cannot state in one number what the home will actually cost to hold each month once the bond payment, CDD assessment, amenity fee, property tax, insurance, and utilities all get combined together.
A Soft Housing Market Adds Even More Uncertainty
Broader housing market conditions add another layer of pressure on top of the fee structure itself. Existing home sales were running at a soft 3.98 million annualized pace as of August 2026, and University of Michigan Consumer Sentiment sat at 55.2 in July, below neutral. A retiree relying on selling their current home to fund a move into this fee structure is doing so amid real uncertainty about how quickly that sale will actually happen.
The Community Does Deliver Something Genuinely Hard to Replace
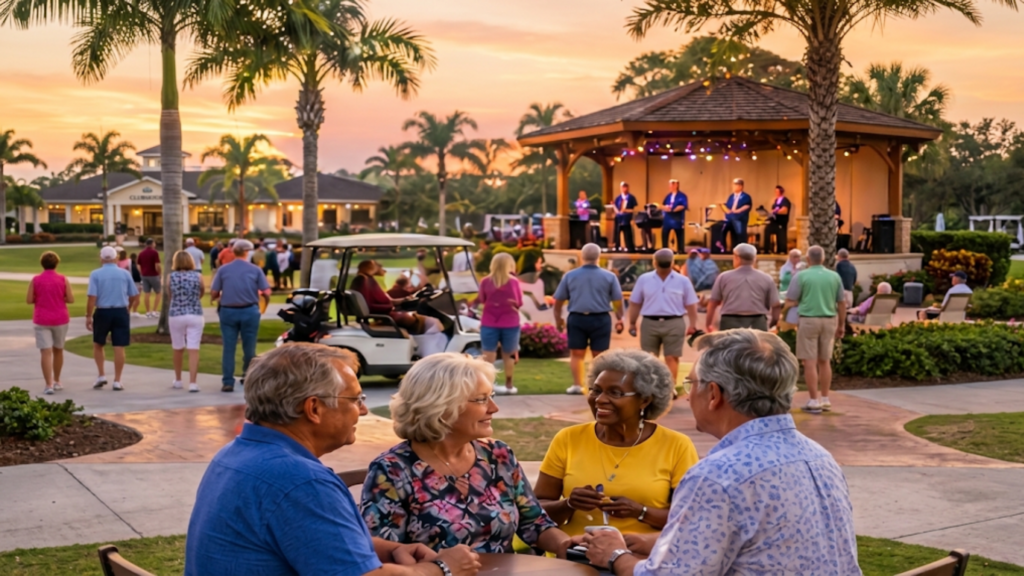
None of this means the community lacks genuine value, walk-aways may actually be undervaluing something real. Building an entirely new social life in your late sixties is genuinely difficult, and The Villages has solved that specific problem at real scale. The nightly town square entertainment and built-in social infrastructure mean a spouse’s death doesn’t necessarily leave the survivor isolated the way it might elsewhere.
The Real Complaint Is Fixed Fees Regardless of Actual Use
For households that use the amenities most days, the monthly fee can feel entirely reasonable compared to private club access elsewhere. The core objection isn’t really about the fee amount itself, it’s that the charge stays fixed regardless of actual usage. A household playing golf twice a month and rarely using the pool ends up paying resort-level pricing for what amounts to occasional, suburban-level use.
Request These Three Documents Before You Even Book the Trip
For anyone seriously considering a purchase, requesting specific documentation before booking a visit can clarify the real math involved. That means asking in writing for the exact bond balance and amortization schedule for a specific home, the current annual CDD maintenance assessment for that district, and the amenity fee’s current escalation clause, then adding property tax and insurance on top of those figures.
One Total Number Tends to Make the Decision For You
Totaling those numbers into a single annual carrying cost, then weighing that total against Social Security and portfolio income with room left for healthcare inflation, is the step many walk-aways say they wish they’d taken before ever booking the trip. The lifestyle preview sells the experience convincingly. The stacked carrying costs are what ultimately determine whether that experience stays affordable for the next 25 years.